3D Tour
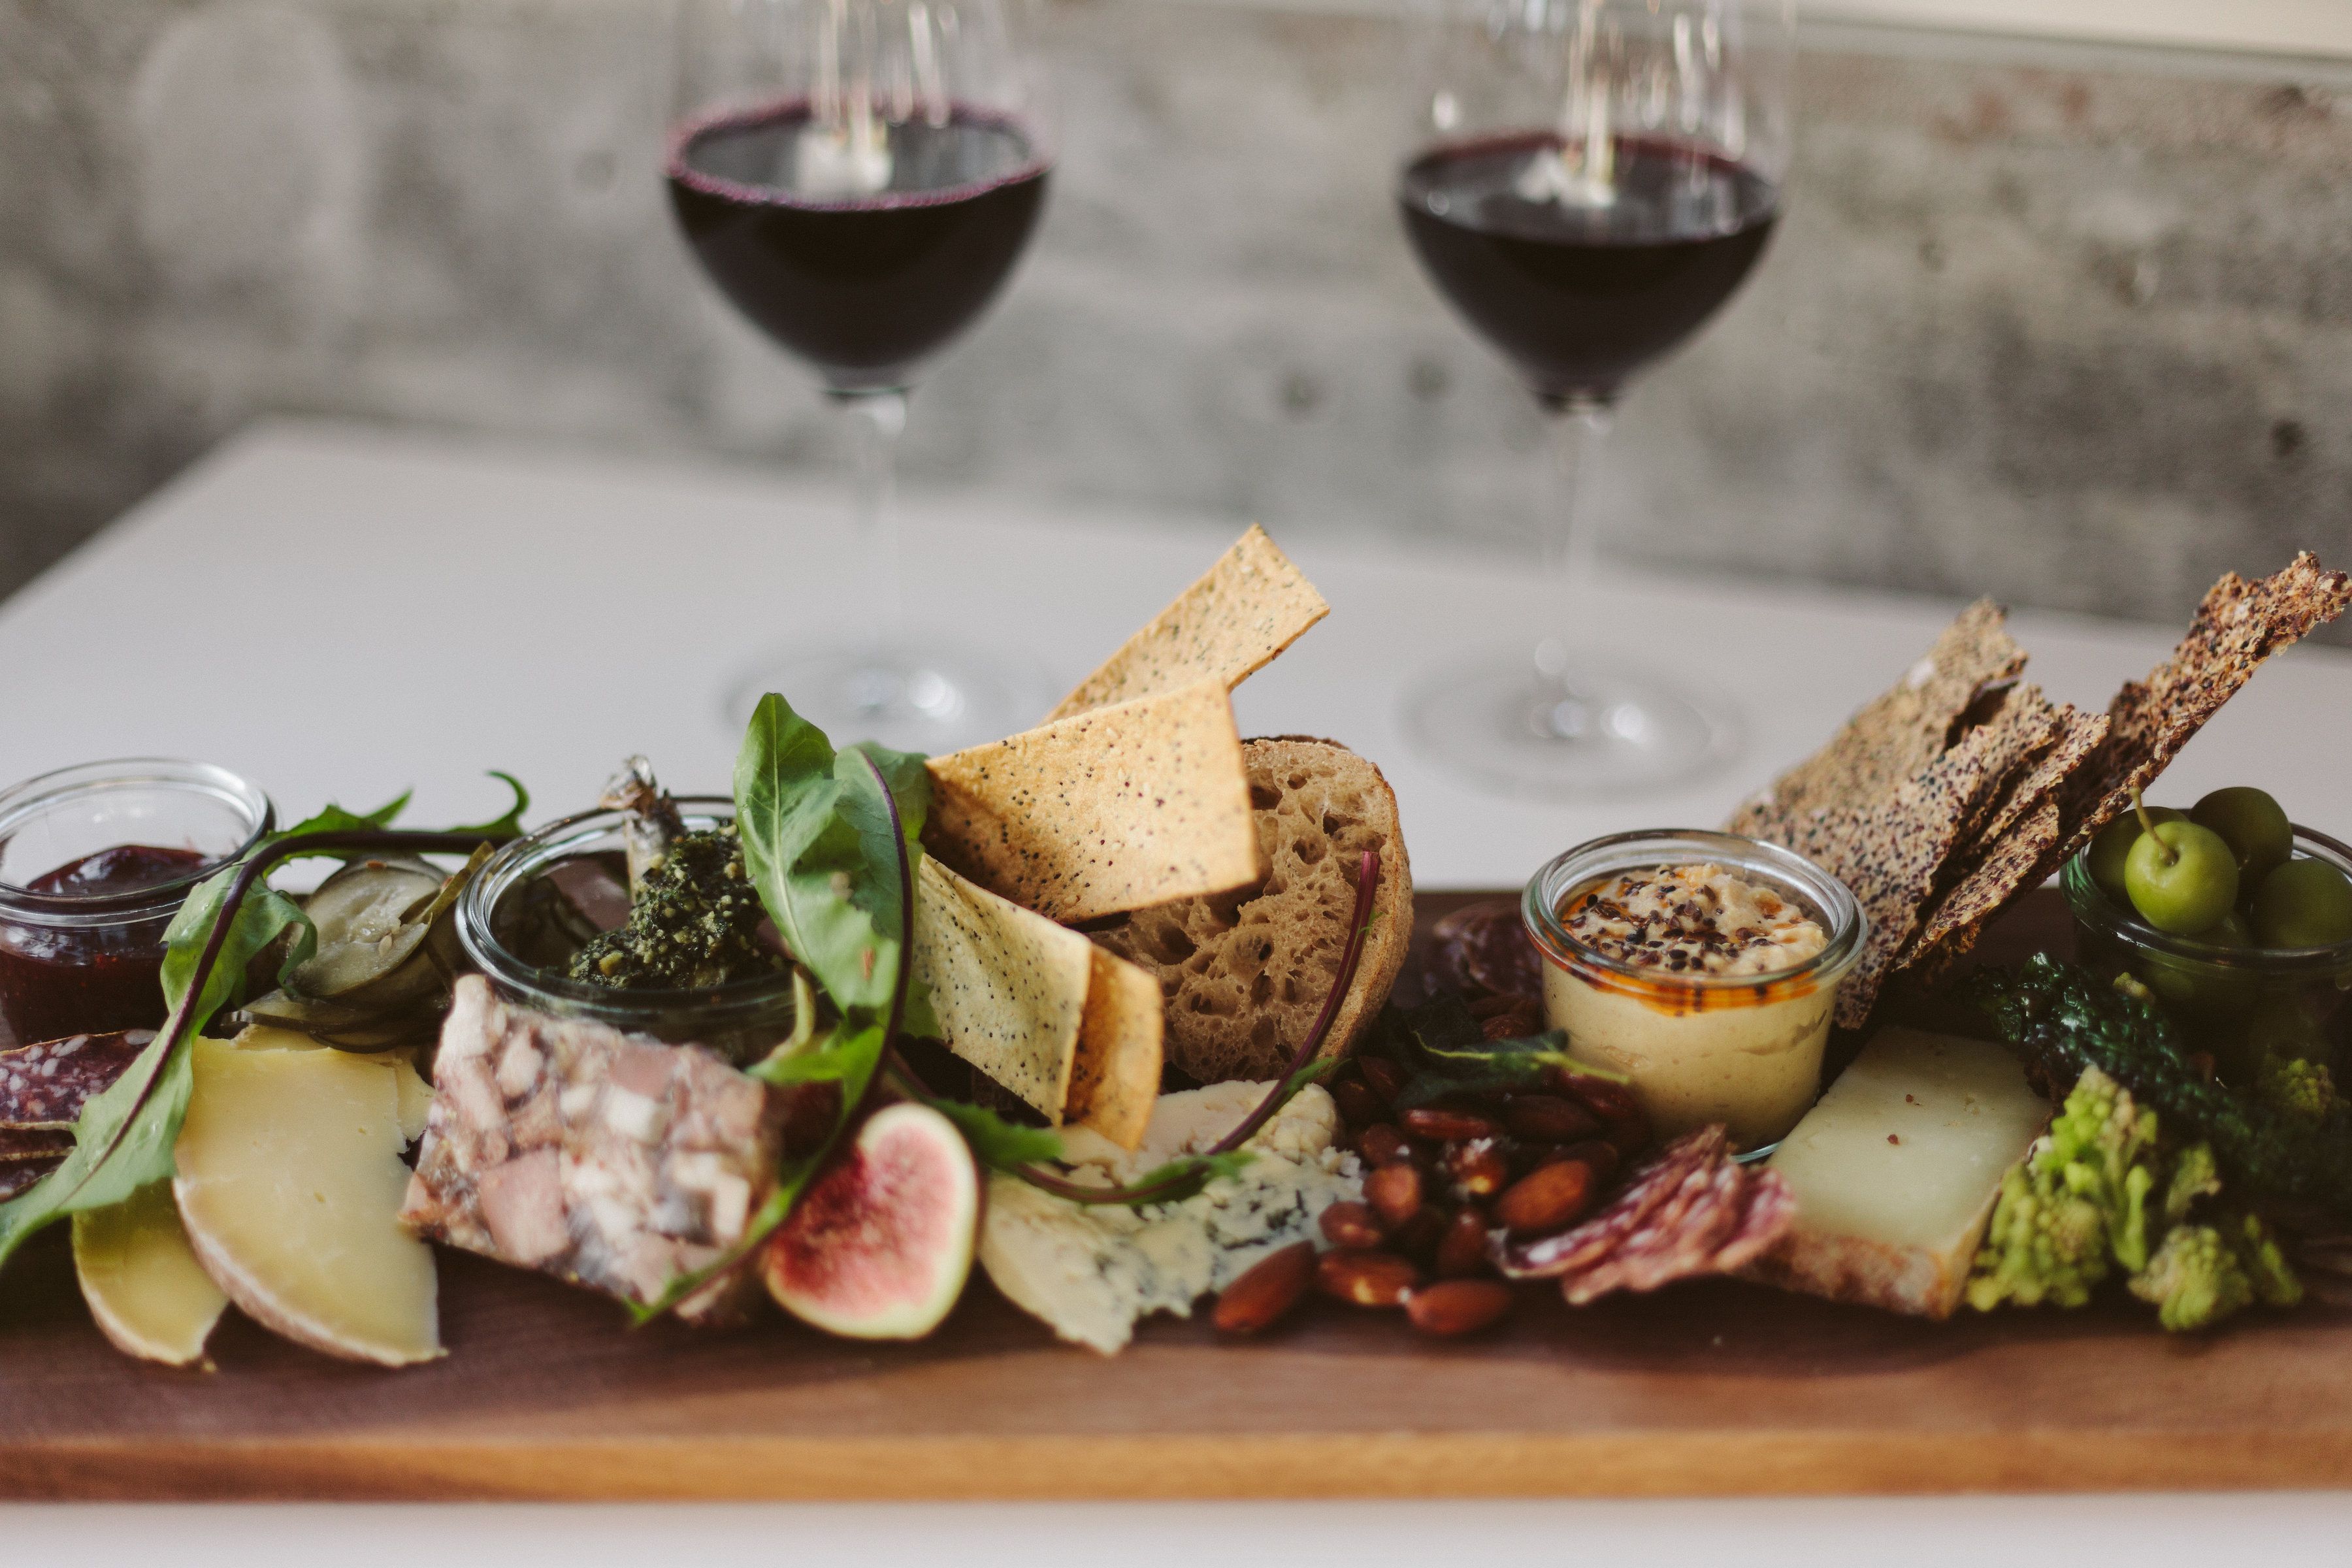
GA Restaurant for sale: LOW rent, SBA Lending-$250,000 Owner Benefit
Albany, Georgia
Restaurants for sale offering restaurant financing provide buyers with an alternative path to business ownership when traditional lending may not be available or desirable. In these transactions, the restaurant seller agrees to finance a portion of the purchase price, allowing the buyer to make payments over time instead of paying the entire amount at closing. Often referred to as seller financing or owner financing, this arrangement can make restaurant ownership more accessible while reducing the upfront cash required to complete the acquisition. For many aspiring restaurant owners, seller financing can bridge the gap between available capital and the total funds needed to purchase a business.
Restaurant financing opportunities can be found across a wide range of concepts, including independent restaurants, cafés, coffee shops, pizzerias, bakeries, bars, quick-service restaurants, food trucks, and full-service dining establishments. In many cases, sellers offer financing because they want to attract a larger pool of qualified buyers, generate ongoing income from the sale, or facilitate a faster transaction. Seller financing is also common when a restaurant may not qualify for traditional bank financing due to limited operating history, inconsistent earnings documentation, or other factors that make conventional lending more challenging.
A typical restaurant financing arrangement involves the buyer making a down payment while the seller finances the remaining balance through monthly payments over a predetermined period. The transaction generally includes a promissory note, repayment schedule, interest rate, and personal guarantees from the buyer. Terms vary significantly depending on the business, the seller's goals, and the buyer's qualifications. In some cases, seller financing is used as the sole source of financing, while in others it may be combined with SBA loans, personal funds, investor capital, or other financing methods.
One of the primary advantages of purchasing a restaurant with seller financing is flexibility. Buyers often benefit from lower upfront capital requirements, reduced lender fees, customized repayment terms, and a potentially faster closing process. Seller financing can also signal that the owner has confidence in the restaurant's future success. However, buyers should still conduct thorough due diligence, review financial records, evaluate cash flow, and understand all financing obligations before moving forward. A restaurant with financing can be an attractive opportunity, but the long-term success of the investment ultimately depends on the strength of the business and the buyer's ability to operate it successfully.
Resources for Buying an Restaurant with Restaurant Financing
Buying a Restaurant is a team sport and you may need all kinds of help. Our Certified Restaurant Broker© team has plenty of resources and aid for you. Here’s a starting point for the most common requests:
Seller financing lets you skip banks, reduce upfront costs, and gain a motivated seller. Not all sellers offer it—but with the right strategy, you can secure flexible terms and close the deal.
New SBA lending rules take effect June 1, 2025, under SOP 50 10 8. Key updates will impact restaurant buyers, sellers, and brokers involved in business sales using SBA financing.
Informative and encouraging guide for restaurant buyers. Breaks down financing options clearly, even in today’s market. Great resource for turning restaurant ownership dreams into reality.
Helpful breakdown of seller financing in today’s market. Explains what owners need to know as banks tighten lending. A must-read for sellers navigating 2023’s evolving deal structures.
Straightforward guide to restaurant financing options and what it takes to qualify. A useful starting point for buyers exploring how to fund their restaurant purchase.
Offers hope for restaurant owners facing SBA or EIDL debt. Explains how an offer in compromise can help settle for less than owed. A valuable read for sellers in tough spots.
Great intro to SBA lending for first-time buyers. Cuts through the confusion lenders may not explain. Trustworthy insights for navigating restaurant financing.
Smart overview of the 5 C’s lenders use to assess risk. A must-read for buyers preparing to finance a restaurant with SBA lending. Know where you stand before applying.
Insightful episode featuring top industry pros discussing restaurant financing. A great listen for anyone exploring funding options or industry perspectives.
Great wrap-up to the financing series—explores crowdfunding as a fresh, community-driven way to fund a restaurant. Ideal for buyers tapping into their personal networks.
Creative and empowering financing tip! Learn how to use your 401K—aka the “Bank of You”—to fund a restaurant purchase without tax penalties or lender rejections.
Owner financing offers key benefits for restaurant deals—faster closings, flexible terms, and fewer lender hurdles. A smart option for both buyers and sellers.
SBA-backed loans offer long terms, low payments, and fixed rates—ideal for big restaurant buys. Just make sure the business has strong financials and tax history to qualify.
Frequently Asked Questions: Restaurant Financing
What does it mean when a restaurant offers financing? It means the seller agrees to finance a portion of the purchase price, allowing the buyer to make payments over time rather than paying the full amount at closing.
Is restaurant financing the same as seller financing? In most cases, yes. Restaurant financing listings typically refer to seller or owner financing where the seller acts as the lender for part of the transaction.
How much of the purchase price will a seller finance? Terms vary, but sellers commonly finance between 25% and 50% of the purchase price, depending on the business and buyer qualifications.
Do I still need a down payment? Yes. Most seller-financed transactions require a down payment, with the remaining balance financed through monthly payments.
Why would a seller offer financing? Sellers may offer financing to attract more buyers, complete a sale more quickly, generate interest income, or demonstrate confidence in the business.
Can restaurant financing help if I don't qualify for an SBA loan? Yes. Seller financing is often used when traditional bank financing is unavailable or when a restaurant does not meet SBA lending requirements.
What documents are required for seller financing? Most transactions involve a purchase agreement, promissory note, personal guarantees, repayment schedule, and other legal documentation prepared by qualified professionals.
What are the benefits of buying a restaurant with seller financing? Benefits may include lower upfront cash requirements, fewer lender fees, flexible deal structures, and faster transaction timelines.
What are the risks of seller financing? Buyers remain responsible for repayment regardless of business performance and should carefully evaluate cash flow, profitability, and financing terms before purchasing.
Do I need a broker when buying a seller-financed restaurant? Not legally, but a Certified Restaurant Broker can help identify opportunities, negotiate financing terms, coordinate due diligence, and guide the transaction through closing.
Is We Sell Restaurants a franchise? Yes, We Sell Restaurants is itself a franchise opportunity, not just a service provider to restaurant franchises. Franchisees become Certified Restaurant Brokers™ through our structured onboarding process, then use We Sell Restaurants' proprietary BOSS (Broker's Operations and Sales System) platform and Restaurant For Sale marketplace to help entrepreneurs buy, sell and lease hospitality properties in their territory.

Buying a Restaurant with Seller Financing
See MoreSBA Loan Changes for Restaurant Buyers and Sellers: What You Need to Know
See MoreThe Ultimate Guide to Financing A Restaurant Purchase
See MoreRestaurant for Sale: Understanding Seller Financing and Owner Financing
See MoreWill I Qualify? Guide to Restaurant Financing
See MoreSelling a Restaurant with SBA Loans Exceeding the Sales Price - Offer in Compromise
See MoreThree Lessons SBA Lenders Won’t Teach You When Buying a Restaurant
See MoreFinancing a Restaurant Purchase? Here's a Review of he 5 C's of Borrowing
See MoreRestaurant Brokers Tackle Financing Option in Radio Show Debut
See MoreCrowd Funding – Financing a Restaurant With the Help of a Crowd
See More


